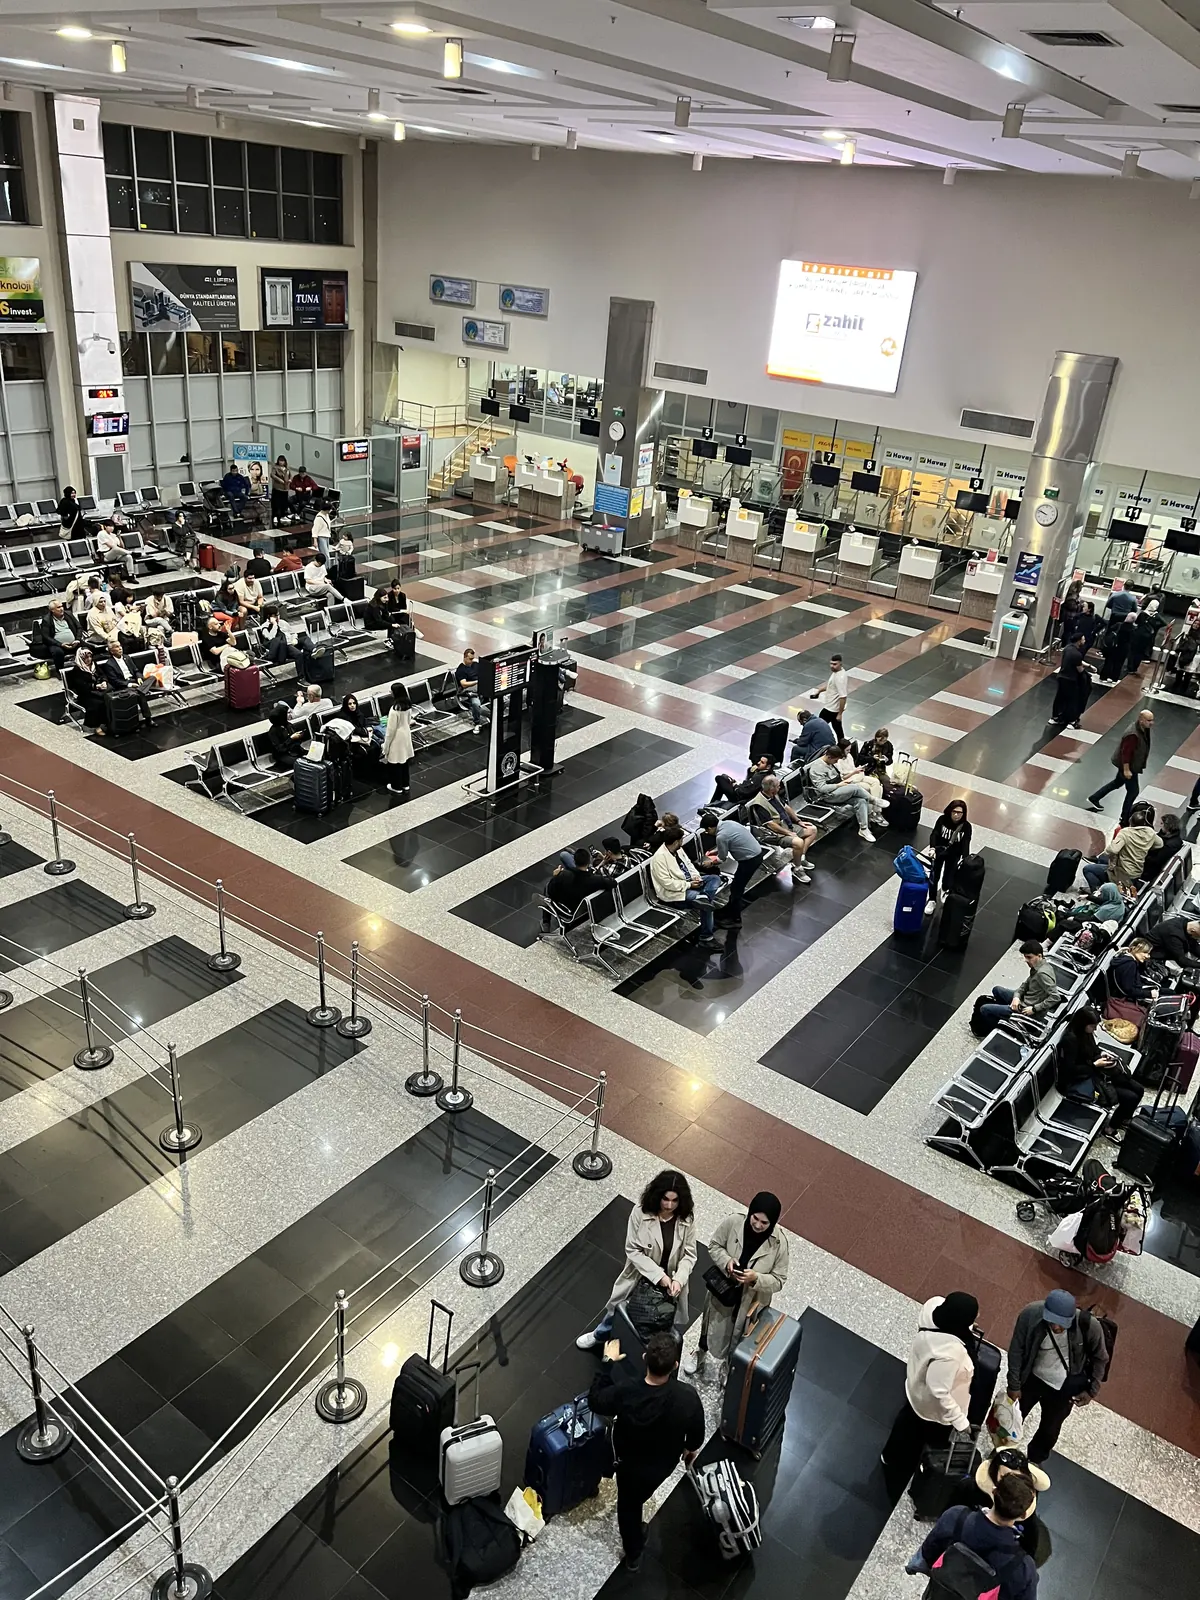
The last flight out of Kayseri was delayed until dawn. Turkish Airlines handed me a meal voucher; every hotel in town was full. So I spent the night at the airport, while a room I had already paid for in Istanbul sat empty.
Surely, I thought, this is exactly what travel insurance is for. It wasn’t.
The claim paid nothing. I have also had the opposite experience: an Etiqa claim that landed in my account before I had even flown home, and another that arrived a full year later, long after I had forgotten I filed it.
Somewhere between those extremes, my priorities changed. Price still matters, but I now care more about the sentence under the number. Does a delay benefit pay for the hours you lost, or only for the receipts you kept? Is that big headline figure for medical bills, or is it a personal accident payout in disguise? The questions get sharper when you compare a standalone policy with the cover that comes free with a credit card.
In this guide
The AIG claim: stranded, but not covered
My flight from Kayseri to Istanbul was pushed to early the next morning. The airline gave me a meal voucher but no hotel, because none was available. So I waited, and the Istanbul room I had prepaid went to waste.
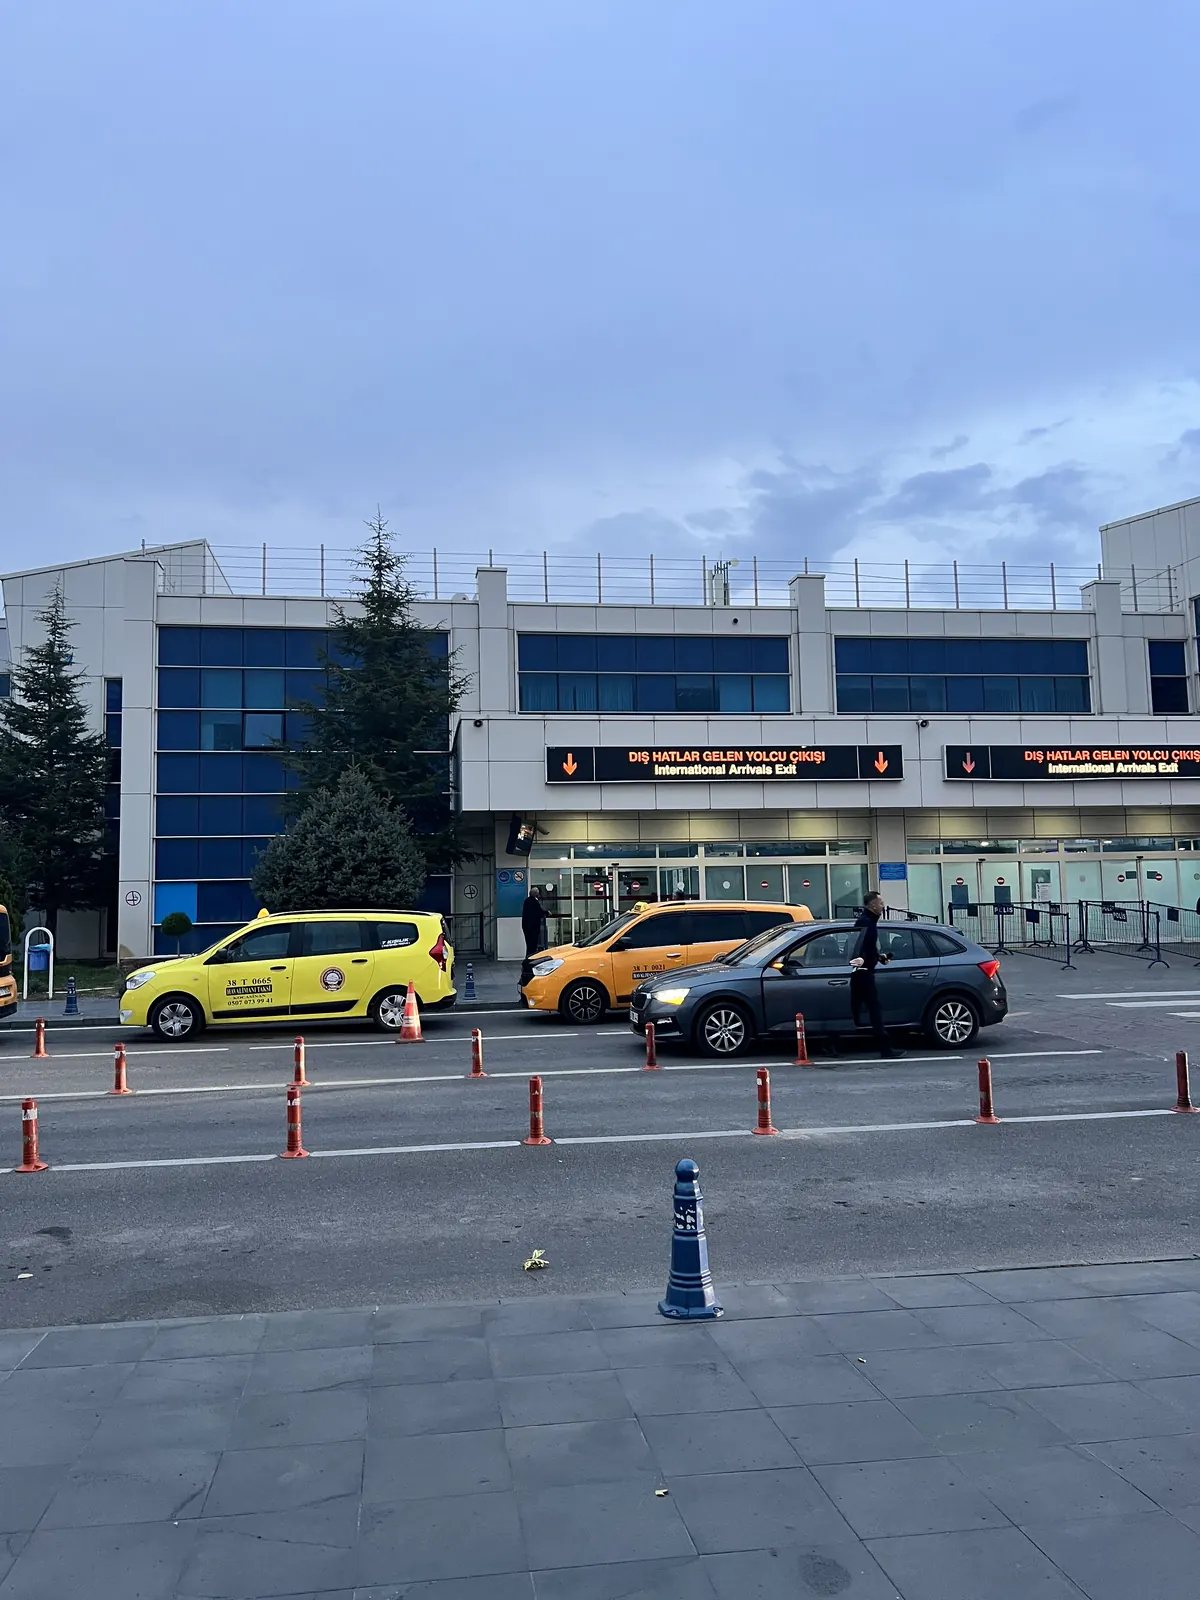
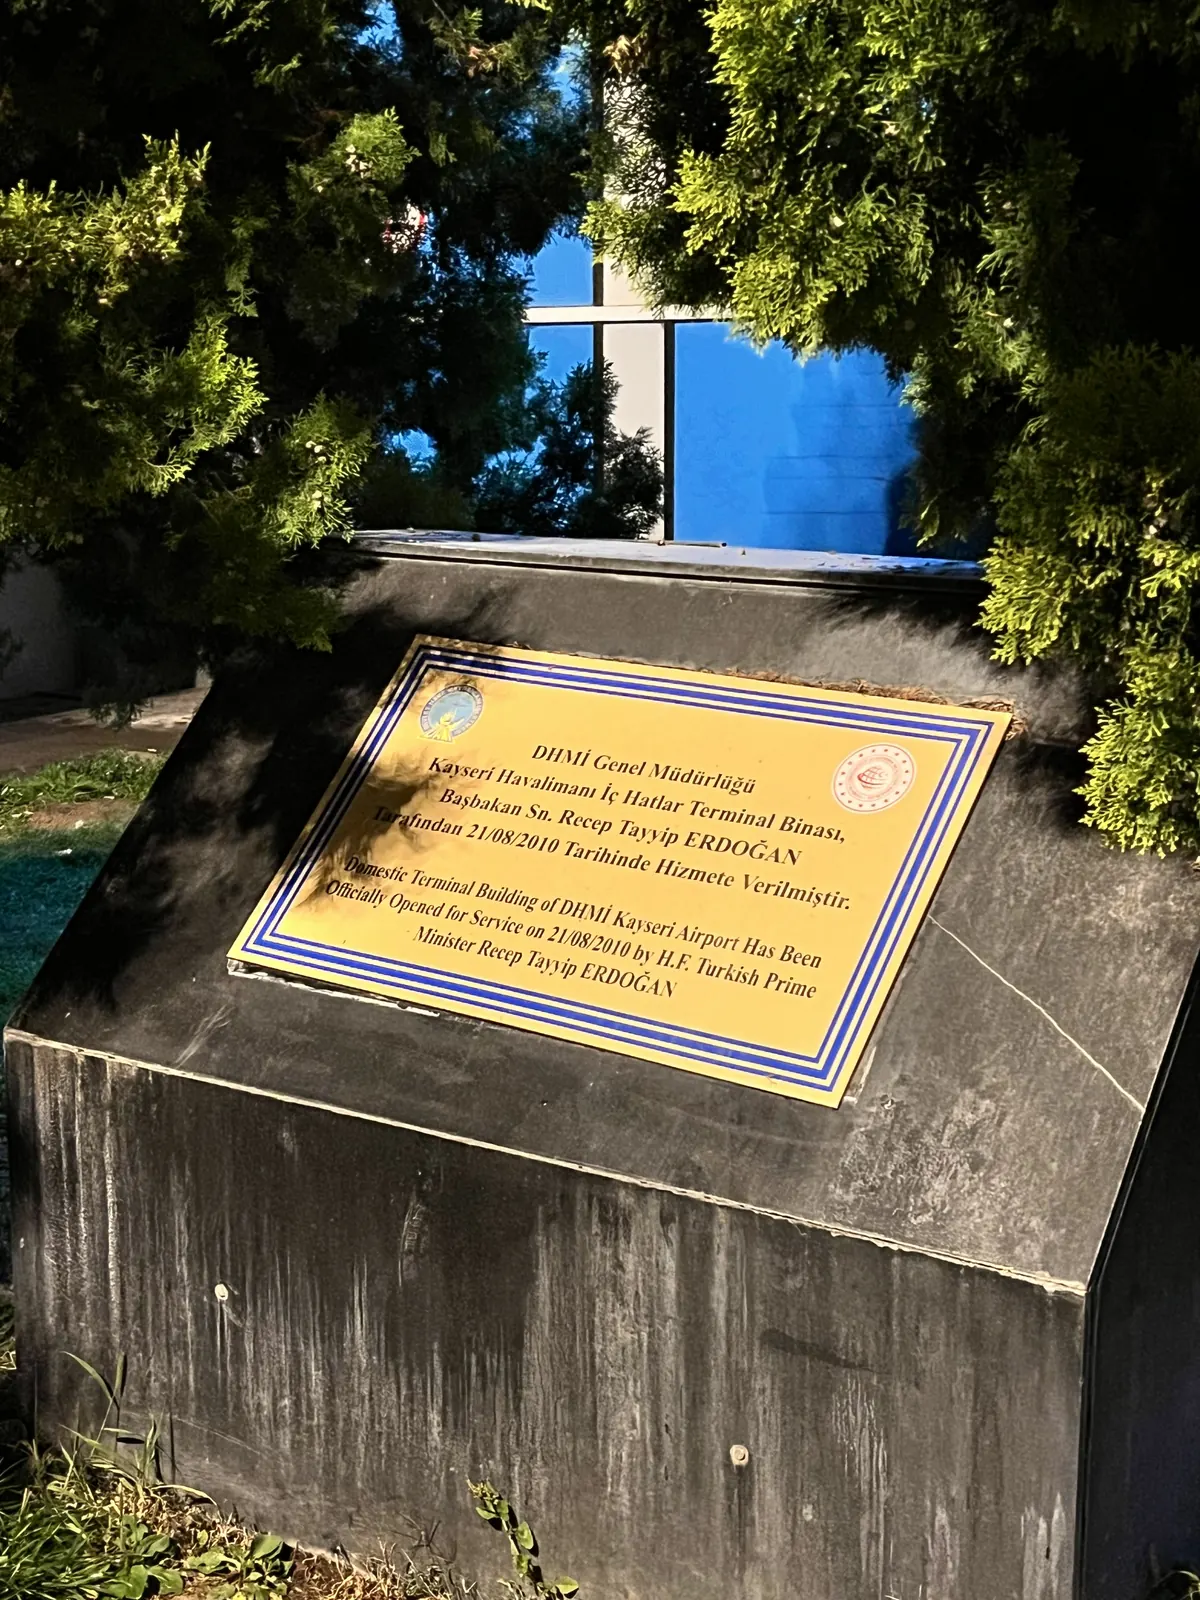
At the time I was relying on AIG cover that came with my HSBC TravelOne card. I assumed an overnight delay would earn something.
AIG’s denial letter explained why it wouldn’t. That benefit reimbursed necessary extra spending on meals and accommodation caused by the delay, and only when nobody else had already provided them free. I had spent nothing extra, so there was nothing to reimburse. The prepaid Istanbul hotel counted as a forfeited expense, which the policy specifically excluded.
From where I stood, the loss was obvious: a night, a lost room, a ruined morning. From the policy’s point of view, I had lost nothing it had promised to cover.
The process wore me down more than the verdict. Replies arrived about once a week and read like form letters, and as I remember it the whole thing dragged on for roughly three months. I would think twice before choosing AIG again. But that is one traveler’s experience of one card policy in 2023, not a verdict on every AIG product. Its current standalone plans work differently, as the next section shows.
“Flight delay covered” can mean two very different things
The biggest lesson from Kayseri was the gap between a fixed allowance and reimbursement. One pays for time. The other pays for receipts.
| Type of benefit | What determines the payout? | What if you spend nothing during the delay? |
|---|---|---|
| Fixed allowance | Length of the eligible delay, per the policy schedule | You may still be paid, if all conditions are met |
| Reimbursement | Eligible extra expenses you actually incurred | You may get nothing, because there is nothing to reimburse |
AIG’s current standalone travel insurance pays a fixed RM150 for every consecutive six hours of eligible delay, with an optional upgrade that pays RM150 for every three. That is structurally different from the reimbursement-based card policy in my claim. You still need proof of why and how long the flight was delayed.
Picture two travelers, each delayed eight hours, each fed by the airline and spending nothing. Under a fixed benefit, both may still be paid. Under a reimbursement benefit, both may get nothing. Same night, opposite outcomes.
Hotels follow the same logic. A new room booked because you are stranded is not the same as a prepaid room at your destination that you cannot use. In my case, AIG’s letter drew exactly that line between additional and forfeited expenses.
Does this benefit pay for the hours I lost, or for the receipts I kept?
Malaysia travel insurance comparison: eight policies, side by side
This comparison covers selected international plans for individual adults. It is not every plan each insurer sells, and the plans are not priced alike. The figures are maximum limits, not automatic payouts; sublimits, exclusions, age bands and claim conditions still apply. MHinsure shows an advertised range; the other rows identify a specific plan. All amounts below are in Malaysian ringgit (RM).
Medical expenses and emergency evacuation
| Insurer and exact plan | Overseas medical maximum | Emergency evacuation / repatriation maximum |
|---|---|---|
 Etiqa TripCare 360 Platinum | RM500,000 | RM1,500,000 |
 Allianz Travel Easy | RM200,000 | RM1,000,000 |
 MSIG Travel SafeGuard Travel Max | RM500,000 below age 65; RM350,000 at ages 65–80 | RM1,000,000 |
 Zurich Travel Guard Go Standard | RM500,000 | RM5,000,000 |
 Tune Protect Travel Easy Basic — standard adult | RM300,000 at ages 18–60; senior Basic RM150,000 at ages 61–80 | RM500,000 |
 MHinsure International — advertised range | Up to RM1,000,000 | Advertised as unlimited |
 AIG Travel Premier | RM10,000,000 for non-COVID medical expenses | Unlimited for non-COVID emergencies |
 Tokio Marine Explorer Deluxe | RM1,000,000 | Unlimited |
Trip cancellation vs. curtailment: what is the difference?
Cancellation is when you cannot start the trip. Curtailment is when you have to cut it short after it has begun. They are separate benefits, with their own covered reasons and limits. A delayed flight does not automatically qualify you for either one.
| Insurer and exact plan | Cancellation: before the trip starts | Curtailment: cutting a trip short | Conditions / shared limits |
|---|---|---|---|
| Etiqa TripCare 360 Platinum | RM50,000 | RM50,000 | Covered reasons only. Cancellation requires purchase at least 7 days before the trip, before a possible disruption is known. |
| Allianz Travel Easy | RM25,000 | RM25,000 | Current PDS limits. Confirm covered reasons and timing in the issued wording. |
| MSIG Travel SafeGuard Travel Max | RM30,000 | RM30,000 | Covered reasons and event timing apply; these limits are for Travel Max. |
| Zurich Travel Guard Go Standard | RM10,000 | RM10,000 | Standard plan. Premium has different limits; do not mix the tiers. |
| Tune Protect Travel Easy Basic — standard adult | RM20,000 | RM18,000 | Basic plan excludes COVID-19; covered reasons still apply. |
| MHinsure International — advertised range | Advertised up to trip value | Advertised up to trip value | Advertised range only. Check each benefit in the selected option; do not assume both pay the full trip price. |
| AIG Travel Premier | RM30,000 | RM30,000 | Premier tier. The reason and claimed expenses must satisfy its wording. |
| Tokio Marine Explorer Deluxe | Within RM70,000 shared category | Within the same RM70,000 category | Shared with postponement/disruption. CFAR is separate in scope: 75% of eligible costs, capped at RM5,000, with booking and cancellation timing conditions. |
Say you prepaid RM6,000, canceled for a covered reason, and recovered RM2,000 from the airline and hotel. That leaves RM4,000 of unrecovered costs to assess—not a RM50,000 payout just because that is the limit. If you cut a trip short and lose four prepaid hotel nights at RM200 each, you have RM800 of unused hotel costs to assess. Whether those costs and a new flight qualify depends on the policy.
Flight delay: what an 8-hour wait might pay
For these examples, assume one eligible eight-hour overseas delay, no extra spending, no earlier claim using the limit, and no optional upgrade unless stated. Only complete qualifying periods count. These are illustrations, not claim guarantees. MHinsure is left uncalculated because its homepage does not identify a matching plan schedule.
| Insurer and exact plan | Delay interval and maximum | Illustrative payout after 8 hours |
|---|---|---|
| Etiqa TripCare 360 Platinum | RM100 after the first complete 2 hours; RM250 for each complete 6 hours after that. Maximum RM5,000. | RM350 |
| Allianz Travel Easy | Current PDS: RM300 per 5-hour period; maximum RM3,000. Older wording differs; confirm the issued schedule. | RM300 under the current PDS illustration |
| MSIG Travel SafeGuard Travel Max | RM200 after the first complete 4 hours, then RM200 for each complete 6 hours after that. Maximum RM3,600. | RM200 |
| Zurich Travel Guard Go Standard | RM150 per complete 6 hours. Overseas maximum RM2,100; Malaysia maximum RM300. | RM150 overseas; RM300 if the paid 3-hour upgrade applies |
| Tune Protect Travel Easy Basic — standard adult | RM200 after the first complete 3 hours, then RM200 for each complete 6 hours after that. Maximum RM3,000. | RM200 |
| MHinsure International — advertised range | The homepage does not give a matching interval and payout schedule. Check the exact option at checkout. | Not calculated: no verified matching schedule |
| AIG Travel Premier | RM150 per complete 6 hours. Overseas maximum RM5,100; Malaysia maximum RM900. | RM150 overseas |
| Tokio Marine Explorer Deluxe | RM200 per complete 6 hours; RM5,000 shared Travel Inconvenience Allowances category. | RM200 |
Baggage claims: delayed, damaged or permanently lost?
Keep these separate. A bag that arrives late may trigger a delay benefit; a stolen or damaged item is assessed under loss or damage cover. A RM10,000 overall limit does not mean a single RM10,000 item is fully insured.
| Insurer and exact plan | Lost or damaged baggage: maximum / sublimits | Baggage delay: interval / maximum | Illustrative 8-hour overseas baggage delay |
|---|---|---|---|
| Etiqa TripCare 360 Platinum | RM5,000 overall; separate sublimits for bags, belongings and electronics. Personal effects: RM500 per article/pair/set. | RM1,000 after at least 6 hours overseas; RM200 on return to Malaysia. | RM1,000 |
| Allianz Travel Easy | Check the issued policy for the overall baggage and per-item limits. | RM200 per 5-hour period; maximum RM3,000, per current PDS. | RM200 under the current PDS illustration |
| MSIG Travel SafeGuard Travel Max | RM10,000 overall; RM500 per article/pair/set, RM1,500 laptop, RM500 suitcase. | RM200 per complete 6 hours; overseas maximum RM1,200, Malaysia maximum RM200. | RM200 |
| Zurich Travel Guard Go Standard | RM3,000 overall; RM500 per item, RM1,000 laptop. | RM150 per complete 6 hours; overseas maximum RM1,000, Malaysia maximum RM200. | RM150 |
| Tune Protect Travel Easy Basic — standard adult | RM5,000 overall; RM500 per item, RM1,000 laptop/golf equipment; RM50 excess per insured person. | RM200 per complete 6 hours; maximum RM1,000. | RM200 |
| MHinsure International — advertised range | Advertised up to RM7,500; check per-item limits in the selected plan. | Check the selected schedule. | Not calculated: check the selected schedule |
| AIG Travel Premier | RM10,000 overall; portable computer/tablet sublimit RM2,000. | RM200 per complete 6 hours; maximum RM2,000. | RM200 |
| Tokio Marine Explorer Deluxe | RM10,000 category; luggage RM300 per unit, other single items RM1,000. | RM200 per complete 6 hours; luggage-delay sublimit RM800. | RM200 |
The baggage-delay examples assume an eligible eight-hour delay at an overseas destination, before any earlier claim uses the limit. They are separate from the flight-delay examples above; they do not show that both benefits can be claimed for the same incident.
For example, MSIG Travel Max lists RM10,000 overall baggage cover but RM500 for an ordinary single article and RM1,500 for a laptop. A RM2,000 jacket therefore still faces the RM500 item cap, before other settlement conditions. Tune Basic also has a RM500 ordinary-item cap and a RM50 baggage excess. These are ceilings, not guaranteed replacement values.
Making a claim: the paperwork that matters
| Claim type | How to think about the payment | Documents to keep |
|---|---|---|
| Flight delay | A time-based allowance counts eligible complete periods. Reimbursement depends on eligible extra spending. | Flight itinerary, boarding pass and the airline’s written delay confirmation showing the reason and actual departure time; receipts if claiming expenses. |
| Trip cancellation | Ask which prepaid costs are non-refundable and whether the cancellation reason is covered. The policy maximum is not a flat payout. | Booking invoices, cancellation/refund confirmations and evidence of the reason, such as the relevant medical report. |
| Trip curtailment | Identify the unused part of the trip and any additional return costs. Their treatment depends on the wording. | Original and revised itineraries, unused-booking/refund records, relevant medical or other evidence, and receipts for additional costs. |
| Baggage loss or damage | The overall limit, per-item cap, excess and valuation can all affect the settlement. | Baggage tags, airline incident report, itemized list, proof of ownership/value, damage photos or repair estimate, and records of the carrier’s settlement. For theft, obtain the police report required by the policy. |
| Baggage delay | A delayed bag is a different claim from a permanently lost one. Confirm whether the benefit pays by time or reimburses purchases. | Baggage tags, airline report and written delivery time. Keep essential-purchase receipts if the policy reimburses expenses. |
Report an incident promptly and check the deadline for the exact policy. Etiqa’s wording, for example, requires baggage loss/damage to be reported to the police or relevant authority within 24 hours and requires a carrier or hotel claim first where they caused the loss. It also prevents claiming baggage delay and loss/damage for the same event and item. That is why I keep the airline’s written report and the final settlement, not just a screenshot of the flight status.
Other conditions before you buy
| Insurer and exact plan | Age, add-ons and other conditions |
|---|---|
| Etiqa TripCare 360 Platinum | International single trip: up to 180 days; annual: up to 90 days per trip. Adventure activities and COVID-19 require the relevant optional cover. |
| Allianz Travel Easy | Rental-car/campervan cover RM3,500 in the PDS. Confirm the wording: this is not a substitute for full vehicle protection. Travel Easy and Travel XPert are different products. |
| MSIG Travel SafeGuard Travel Max | Age changes the medical limit. Optional cruise and alternative-transport benefits must be selected; they are not automatic. |
| Zurich Travel Guard Go Standard | Rental-car excess RM2,000. Paid delay upgrade changes the interval to 3 hours; winter sports/scuba require the Special Sport rider. |
| Tune Protect Travel Easy Basic — standard adult | Basic excludes COVID-19. Outpatient medical claims carry a RM50 excess; mountain-sickness claims carry a RM200 excess. |
| MHinsure International — advertised range | Underwritten by Etiqa, with separate wording from TripCare. These are advertised range limits, not one verified tier. |
| AIG Travel Premier | Single overseas trip: up to 180 days; annual: 90 days per trip. COVID medical/evacuation has a separate RM800,000 limit. |
| Tokio Marine Explorer Deluxe | CFAR: 75% of eligible flight/accommodation costs, maximum RM5,000. Bookings within 14 days before policy purchase; cancel more than 48 hours ahead. |
“Up to” is a ceiling, not the amount you automatically receive. “Unlimited” evacuation still requires a covered emergency and the insurer’s assistance arrangements. Allianz’s PDS and older wording show different delay terms; confirm the documents issued with your purchase.
A plan’s name tells you very little. A Platinum plan from one insurer can be weaker in some respect than a mid-tier plan from another.
Etiqa: big cancellation cover, but only for covered reasons
TripCare 360 Platinum offers trip cancellation up to RM50,000, against RM20,000 under Gold. Silver has none. But this is not “cancel for any reason.” Your reason must fall within the wording, and the policy sets timing requirements too.
Cancellation cover matters most when you have sunk serious money into non-refundable bookings. A trip of refundable hotels is a very different risk from one built on prepaid flights, tours and non-refundable stays.
Allianz: “cashless” has a threshold
Allianz Travel Easy offers cashless admission and discharge for overseas hospital bills above RM20,000 per admission. That does not mean every clinic visit or small bill is handled without paying upfront. Before I fly, I want to know whom to call in an emergency, how admission works and what documents I will need.
MHinsure and TripCare are not the same product
MHinsure is underwritten by Etiqa, but it has its own benefit schedule, wording and claims process. My experience with one Etiqa product does not automatically carry over to the other. MHinsure’s FAQ states a target response time of 20 working days, counted from receipt of any extra documents requested. That is a response target, not a promise of payment within 20 days.
Buying cover alongside a Malaysia Airlines ticket is convenient. Read the policy anyway.
Tokio Marine CFAR: a partial refund, with conditions
Explorer Deluxe includes a Cancellation for Any Reason benefit. It pays 75% of eligible prepaid, non-refundable flight and accommodation costs, up to RM5,000. You must cancel more than 48 hours before departure, and the expenses must not have been paid more than 14 days before you bought the policy. So if RM4,000 of eligible costs qualify, you get RM3,000, not RM4,000.
A big baggage limit is not full value for every item
Tokio Marine Explorer Deluxe lists up to RM10,000 for personal belongings, yet per-item sublimits still apply. That is why I read the per-item limits, not just the headline.
My Etiqa claims: sometimes fast, once a year late
Etiqa’s big advantage is convenience. The Etiqa+ app lets you submit documents and track a travel claim. On one trip, the money arrived while I was still abroad.
Another claim went differently. I submitted it through the app, never followed up, and the payment turned up about a year later. By then I had forgotten it entirely.
So: the filing process is easy, in my experience. Fast payment is another matter, and I would never promise it.
What other travelers report
Public reviews help only when they say what was claimed, which documents were requested, how long it took and how it ended. Take every one below as a single account, not a ranking.
Etiqa: more than 40 days without progress
An App Store reviewer, writing on 23 June 2025, said a flight delay claim filed through the app had not moved in over 40 days, while another passenger on the same flight was reportedly paid after emailing a claim later.
Etiqa: settled within days
On r/MalaysianPF, another user said their claim was settled within a few days once every document was in.
Tokio Marine: a RM6,308 dispute
In a December 2025 reader letter to CodeBlue, a policyholder described a dispute over RM6,308 in cancellation claims. One earlier claim was approved; two later ones were rejected over pre-existing conditions and hospitalization requirements. The claims date from 2023 and 2024, so they say little about how the renewed 2026 Explorer would treat CFAR.
I would not crown any insurer “easiest to claim from” on a handful of online posts. Reviews tell you about communication and process. The wording tells you what is covered.
The insurance that comes with your credit card
Complimentary card insurance can be genuinely useful, but the headline number can mislead. A RM1 million figure, for example, may be a personal accident benefit rather than medical cover.
| Card and insurer | Overseas medical | Flight delay and key conditions |
|---|---|---|
| HSBC TravelOne (AIG) | USD250,000 | Reimbursement of eligible meals and accommodation after a four-hour threshold†. Register before travel; full-fare payment conditions apply. |
| CIMB Travel World Elite (AIG) | USD500,000 | Delay reimbursement up to USD500 after four hours. The fare must meet the card or rewards-payment conditions. |
 CIMB Travel World / Travel Platinum (Berjaya Sompo) | RM25,000 individual; RM50,000 family | No standard flight delay benefit confirmed in the policy referenced here†. CIMB’s site separately advertises USD100,000 travel medical for Travel World, so check which applies. |
 UOB PRVI Miles Elite (Liberty) | RM100,000 | Reimbursement after four hours, up to RM2,500 individual or RM5,000 family. Full fare must be charged to the card. |
| Maybank 2 Cards Premier (American Express Reserve) | No normal overseas medical limit in the certificate; the RM1 million headline is personal accident | Up to RM800 for the cardholder and RM800 for covered family members for a delay of more than four hours. Travel must be charged to the card. |
| Standard Chartered Journey (AIG Core) | USD100,000 | No standard flight delay benefit listed in the Core schedule†. Register before travel; fare or rewards-payment conditions apply. |
Similar card names, very different insurance
CIMB Travel World Elite does not share an insurance schedule with CIMB Travel World or Travel Platinum. The Elite policy gives USD500,000 in medical cover. Travel World and Platinum, under the policy referenced here, give RM25,000 for an individual, while RM50,000 is a family limit, not RM50,000 for each person. Mix currencies, individual limits and family limits together and a promotional page becomes very easy to misread.
“Up to RM2,500” is a ceiling, not a payout
UOB PRVI Miles Elite reimburses eligible delay expenses up to RM2,500 for an individual. If your eligible expenses come to RM80, you get RM80. This is why I compare how a benefit pays alongside the size of the number.
Owning the card does not mean the cover is on
HSBC TravelOne and Standard Chartered Journey both require registration, according to the documents referenced here. Paying for the ticket does not complete every step, and the payment channel can matter too. I keep the certificate, proof of registration and proof of payment with my itinerary. Those are worth more in a claim than a screenshot of the card’s marketing page.
Award tickets and miles: do not assume you are covered
Some card policies accept fares paid with eligible reward points, but the wording is everything. The HSBC policy requires the entire common-carrier fare to be charged to the eligible card or acquired with points from a rewards program tied to that card, and registration before the trip.
I would not assume that paying only the taxes and fees on an award ticket switches the insurance on. Check the redemption arrangement, where the points came from and the payment rules in the certificate, and ask the insurer to confirm in writing if anything is unclear. Keep the redemption confirmation, the receipt for taxes and fees, and proof of the payment or points with your policy documents.
Rental-car insurance: check what needs separate protection
I do not treat Malaysian travel insurance as my vehicle protection. For a road trip in Europe or the United States, I prefer to take suitable rental protection when I book or collect the car.
Some travel policies do reimburse a rental-car excess. Zurich Standard lists RM2,000, for example. That is the deductible you may owe under the rental vehicle’s insurance; it does not turn your travel policy into complete damage, theft or liability protection.
Check what the price already includes, what extra protection is on offer, and what you would still pay if something happened. Damage, theft and third-party liability are separate questions, and one product labeled “insurance” rarely answers all three. For a motorcycle, ask for written confirmation that the cover applies to that bike and that rental.
Italy: I took Hertz protection despite an Amex Platinum
I carry a US-issued American Express Platinum, which includes rental-car damage and theft protection on eligible rentals. Its standard benefit excludes vehicles rented in Italy and includes no liability cover. The paid Premium Car Rental Protection option excludes Italy as well.
When I rented from Hertz in Italy in 2024, I took Hertz’s protection, because my Amex benefit could not be relied on there. Now I never decline cover at the counter just because my card lists car rental insurance. I check the country, the vehicle, the payment requirements and the exclusions first. For me, proper rental protection belongs in the road-trip budget.
Seven questions before you buy
The experience I most want to avoid is learning what a benefit means only when I need to claim. So I ask:
- Medical or personal accident? Is the headline number for medical bills, or for an accident benefit with a different purpose?
- Allowance or reimbursement? Does the delay benefit pay for hours delayed, or only for extra expenses with receipts?
- Which costs can I lose? Are my non-refundable flights, hotels and activities covered for the reasons I worry about?
- What are the smaller limits? What are the per-item, age, individual and family limits behind the headline amount?
- Is the cover active? Have I met the registration, payment, booking and trip-length conditions?
- What needs separate protection? Do my rental vehicle or planned activities need their own arrangements?
- How do I claim? Which number do I call, which documents must I keep, and how will I track the claim?
AIG taught me to read how a benefit pays. Etiqa taught me the difference between an easy filing and a fast payout. A Hertz counter in Italy taught me that even a premium card has borders.
These are the details I compare before I look at the price. Ask yourself what exactly the policy will do for you on the worst night of the trip.
Sources and policy documents
Benefit figures come from the insurers’ and banks’ own documents: AIG Travel, Allianz Travel Easy, MSIG Travel SafeGuard, Zurich Travel Guard Go, Tune Protect Travel Easy, MHinsure, Tokio Marine Explorer CFAR, HSBC TravelOne, CIMB Travel World Elite, CIMB Berjaya Sompo, UOB PRVI Miles Elite, Maybank 2 Cards Reserve, Standard Chartered Journey and American Express Platinum. Customer accounts come from the App Store, r/MalaysianPF and CodeBlue, as linked above. Claim experiences are my own. Detailed schedules: Etiqa benefit document, Allianz benefit document, MSIG benefit document, Zurich benefit document, Tune benefit document, Mhinsure benefit document, AIG benefit document, Tokio benefit document.
The conversation
Questions, tips & experiences.
Have a question about this guide, or a useful travel tip? Every comment is reviewed before it appears.
0 comments
Be the first to share a question or a helpful tip.